


SEMI Market Overview
July 8, 2013, Semicon West, San Francisco—Dan Tracy from SEMI presented an overview of the industry with a focus on equipment and materials. The market numbers indicate an ongoing recovery after a slow period in the past two years.
World wide, the industry has had a relatively flat income for the last two years, with low single-digit growth and ongoing uncertainty. Semiconductor equipment has been added in foundries and flash memory facilities and some added for the 28 nm to 20 nm transition. DRAM and other products are getting small upgrades to meet the demands for mobile devices and to update technologies.
Essentially, there has been no new capacity in the semiconductor industry in the past two years. Capital expenditures are dominated by the top 5 manufacturers; Intel, Samsung, TSMC, Global, and Hynex, as a result, the pullback in equipment from these companies drove the whole market down. Next year, these companies are planning some major projects for new fabs and for new fab equipment.
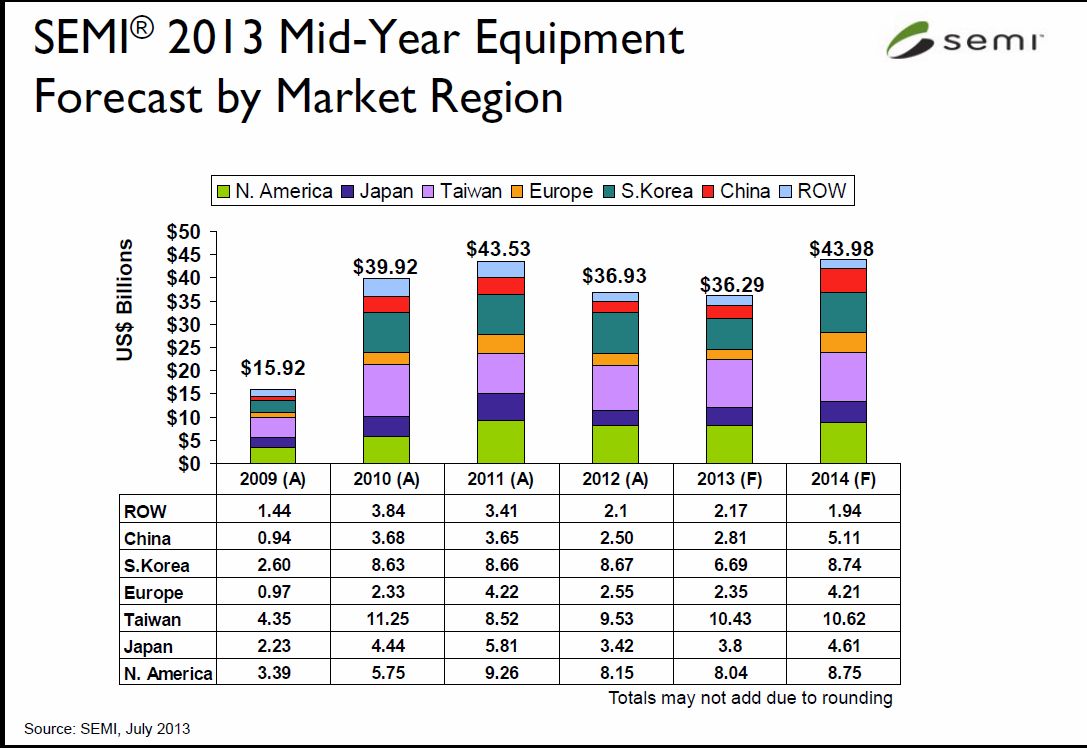

The forecasts by region and product category are shown in figures 1 and 2. Forecasts for packaging equipment predict 6 percent growth next year and materials will increase 2 percent. There is dollar pressure on some materials and wafer prices should drop. Some of the materials changes are driven by the change from gold to copper wires.
In the coming year, North America will be one of the biggest drivers for semiconductor investments and equipment and materials should grow about 20 percent in ’14. the materials portion will increase from $48B to $50B in that time. The transition to 20 nm will dominate the major equipment purchases, and will drive the range of materials into wider categories.
