


CES 2014 – Global trends presentation
January 2014 – Steve Koenig, Industry Analysis Director for the Consumer Electronic Association (CEA) delivered his presentation to the media paraphrasing the Julius Verne book “Around the World in 60 minutes”. The presentation updated the global technology market provided by GfK and CEA. GfK is a Boutique Research organization and is a wholly-owned subsidiary of GfK Retail and Technology producing forecasts, supply chain metrics, and other analysis. Retail CE sales track more than 340,000 retail stores in 80 countries. CE Market Metrics, a service of CEA, tracks US factory to dealers’ shipment in more than 50 CE categories on a weekly and monthly basis. Analysis considerations are geographical and financial. The agencies divided the world into two categories of countries: mature and developing. Just for clarification Koenig stated that mature countries include North America, Western Europe, and developed APAC; developing countries are in Central and Eastern Europe, Latin America, Emerging APAC and Middle East /Africa.
Koenig started with a statement that in 2014 that 43 cents on every dollar will be spend on technology. “As you remember” said Koenig “not a long ago books were everywhere around the house: in living room, in bedroom and in the kitchen. Now books are replaced by tablets and TV, and 2014 will bring more density of these devices per household.”
According to Koenig, the Global Tech Markets returned to growth in 2013. Koenig gave a quick review of global markets starting from 2010, which was a year of economic recovery and the entire world spent $922 billions, representing a 10percent growth compared to 2009. The next year brought 13 percent growth to $1041 billions, with leading categories of smartphones and tablets. In 2011, emerging market strength offset sluggish developed markets. In 2012, dollar value was hit by currency weakness outside North America and reached $1034 billions in sales. This year brought negative growth of 1 percent. 2013 was better for global tech markets, spending grew 3 percent with total spending of $1068 billions. Smartphone and tablet growth offset decline in other products. GfK and CEA forecasts $ 1055 billions spending for 2014 with 1 percent decline. The key points of 2013 are:
1. Sales growth for tablets and smartphones slowing, but remains robust compared to other categories
2. LCD TV still growing in low single digits
3. Year-end push from next-gen game consoles
4. Some spending momentum in North America
Reasons for spending decline in 2014:
1. Volumes: Unit growth in tablets and smartphones reliant on low-end devices. ASPs coming down fast
2. Product/Pricing Mix: Lower end devices (and ASPs) required to penetrate lover consumer tiers of emerging markets
3. Impact to Tech Spending: Developing market spending growth curbed somewhat and not enough to offset spending declines in developed markets and CE categories
Regional Spending Growth Picture in 2014 remains mixed.
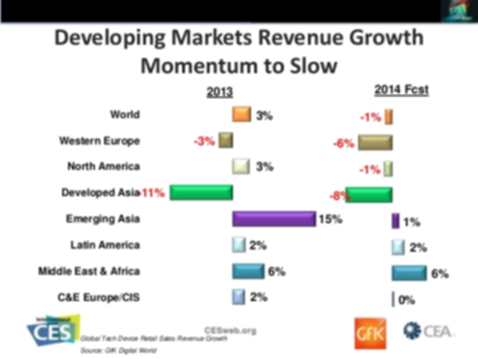


Mobile and connected devices continue to drive the tech spending in 2014. The Smartphone and tablet revenue contains 43 percent of entire revenue from all consumer electronics devices and is now offsetting contraction elsewhere. In the tablets category, lower-priced models are boosting adoption in emerging markets. The North America market in 2012 was 40 percent, in 2014 it will be 33 percent; other developed markets in 2012 were 31 percent, in 2014 dropping to 25 percent. Emerging markets reverse these numbers: in 2012 tablets represented 29 percent, growing to 42 percent in 2014. In the Smartphone category, emerging markets take the lead as lower-price devices open up the mass market. In 2011 emerging markets made 48 percent of global Smartphone sales and growing to 70 percent in 2014. Global ASP for Smartphone declined from $444 in 2010 to $345 in 2013 and will remain as low as $297 in 2014.
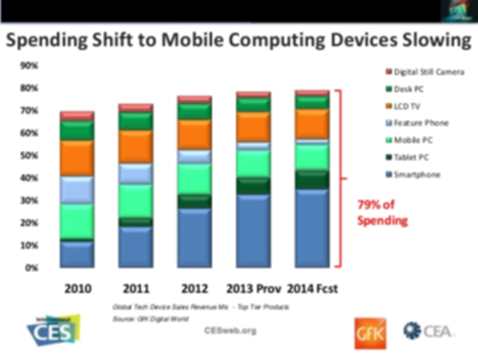

As we see, almost 80 percent of global spending on CE is on 8 categories of devices and the old technologies continue to be squeezed out.
Global TV Sales Trends Key Points:
1. Average screen size continues to grow
2. 3DTV growth tapering off. Top vendors not pressing
3. Smart TV: popular as well in China
4. New Tech Ushers in The Next Wave of Innovation:
A. UHD: Expect global shipments of 8.7 million in 2014
B. Curved displays
C. OLED (<500k units in 2014)
